Market Analysis ·
Cross Margin vs Isolated Margin for Traders
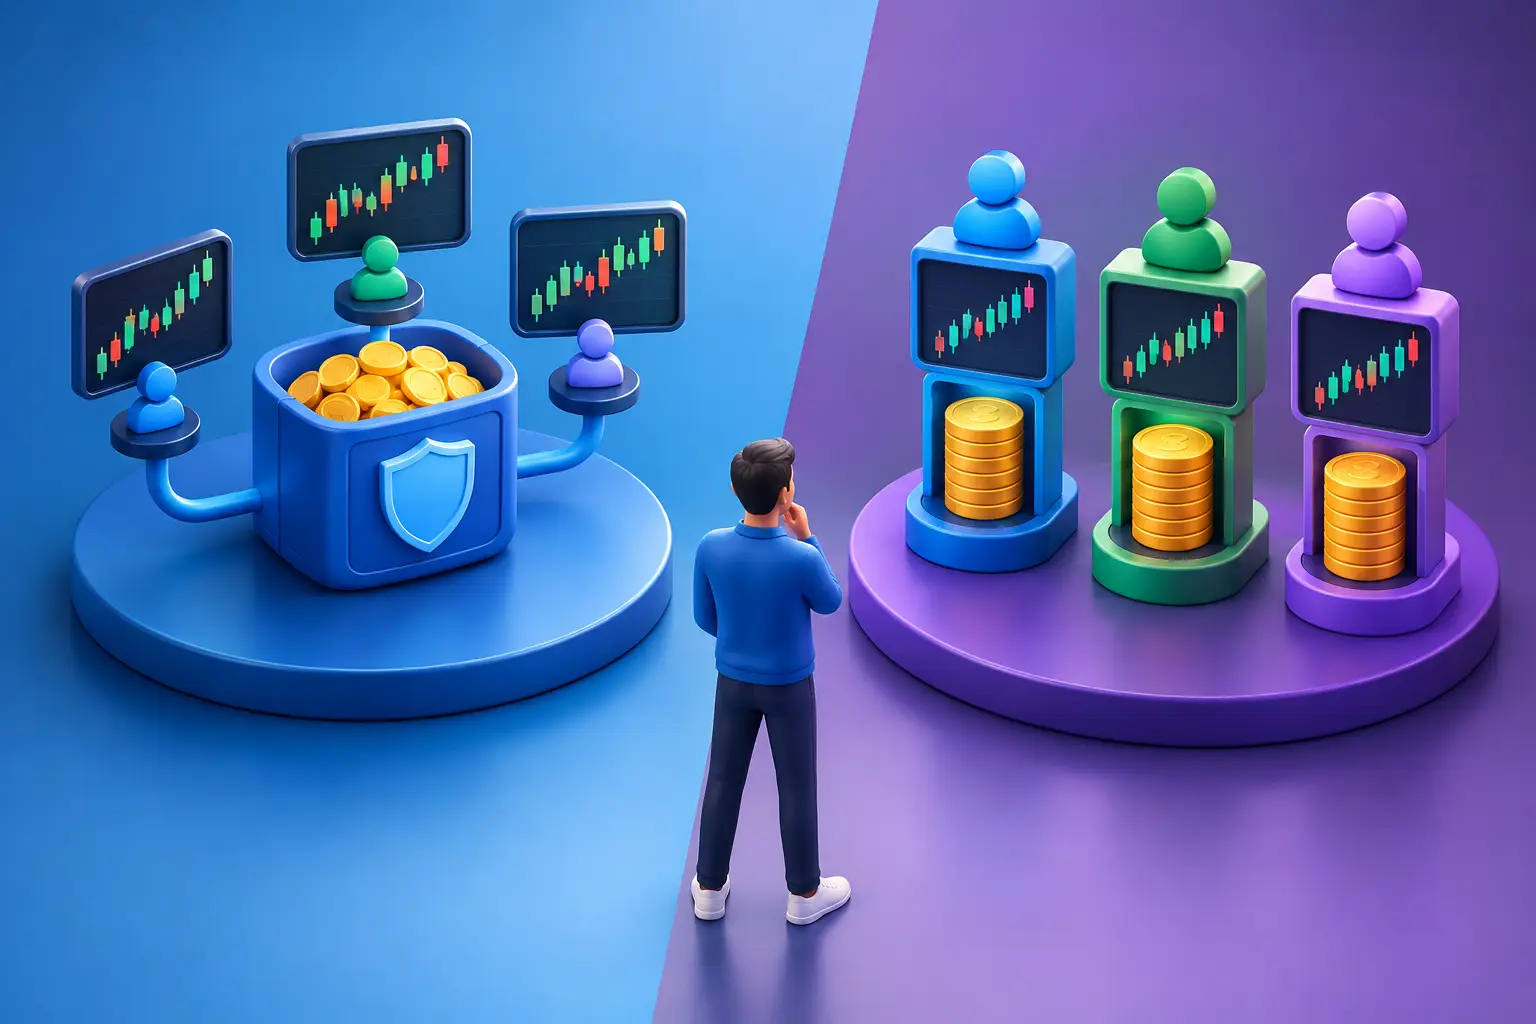
A clean market structure shift, a well-defined order block, and a properly timed entry can still produce a bad trading outcome if the margin mode is wrong. Cross margin vs isolated margin is not a minor exchange setting. It determines whether one losing perpetual futures position can consume collateral intended for the rest of your account.
For traders using Smart Money Concepts or ICT methodology, margin selection belongs inside the execution plan. Your directional thesis, entry model, invalidation point, position size, leverage, and collateral structure must work together. If they do not, a technically valid setup can become an account-level risk event.
Cross Margin vs Isolated Margin: The Core Difference
Margin is the collateral an exchange holds to support a leveraged position. When price moves against you, the exchange uses that collateral to cover unrealized losses and keep the position open. If collateral falls below the maintenance margin requirement, the position may be liquidated.
With isolated margin, you assign a specific amount of collateral to one position. That position is ring-fenced from the rest of your futures balance, unless you manually add more margin. If the trade fails, the loss is generally limited to the collateral allocated to that position, plus fees and any other exchange-specific charges.
With cross margin, your available futures collateral can support multiple open positions. A losing position may draw on the broader account balance to avoid liquidation. This can give a trade more room to fluctuate, but it also means one position can put capital allocated to other trades at risk.
The decision is therefore simple in principle but consequential in practice: isolated margin contains risk at the position level; cross margin manages risk at the portfolio level.
Isolated Margin: Defined Risk per Position
Isolated margin is usually the more appropriate starting point for a trader building consistency. You decide the collateral attached to the trade before execution. If your idea is invalidated, the damage has a predefined boundary.
Consider a trader with $5,000 in a futures account who allocates $250 of isolated margin to a BTC position. If the position is liquidated, the intended maximum exposure is concentrated around that $250 allocation rather than the full account balance. The exact liquidation loss can vary based on fees, funding, maintenance requirements, and whether extra margin was added, but the core benefit remains clear: the trade cannot automatically consume the remaining $4,750.
This structure aligns with a process-driven SMC approach. A trader identifies liquidity, waits for displacement, confirms a market structure shift, enters from a refined order block, and defines invalidation. If price reaches the level that proves the idea wrong, capital should be protected for the next qualified setup.
Isolated margin does not make high leverage safe. A 50x position with a tight liquidation threshold can still be reckless, even when only a small portion of the account is allocated. The advantage is containment, not permission to oversize.
Cross Margin: Shared Collateral Across Positions
Cross margin is designed for traders who actively manage total portfolio exposure. Rather than assigning a fixed amount to each trade, the account’s available collateral is shared. Profits from one position may support losses in another, while losses can reduce the margin buffer across the account.
This can be useful when positions are intentional parts of one larger thesis. For example, a trader may hedge spot BTC exposure with a perpetual short, or hold several derivatives positions whose aggregate delta and risk have been calculated. In these cases, evaluating each position in isolation may hide the true portfolio picture.
The danger appears when cross margin is used without portfolio-level controls. Three correlated long positions in BTC, ETH, and SOL may look diversified because they are separate markets. During a broad risk-off move, however, they can decline together. Cross margin allows the losses from all three positions to draw down the same collateral pool.
A trade that would have been cleanly stopped or liquidated under isolated margin can remain open longer under cross margin. That sounds helpful, but it often encourages hope rather than disciplined decision-making. More time is valuable only if the position still respects the original thesis and risk parameters.
Liquidation Is Not a Stop-Loss
Many newer futures traders confuse liquidation protection with risk management. They are not the same thing.
A stop-loss is a planned exit placed at the price level where the trade thesis is invalidated. In an ICT-style model, that might be beyond the swing that should not be breached if your read on order flow is correct. It is an analytical decision.
Liquidation is an exchange mechanism. It occurs when your remaining margin no longer meets the exchange’s maintenance requirements. It may happen far beyond the point where your original trade idea was already invalid. Waiting for liquidation turns risk management over to the platform.
This distinction matters especially with cross margin. Because shared collateral can delay liquidation, traders may mistake a wider survival range for a better trade. It is not. If price trades through your invalidation, the correct question is not, “Can this account absorb more drawdown?” It is, “Does the market still support this thesis?”
How Leverage Changes the Decision
Leverage increases position size relative to collateral. It does not improve the quality of an entry, strengthen market structure, or reduce the probability of loss. It simply makes price movement matter more.
A trader using 10x leverage controls a larger notional position than the margin posted. At 25x or 50x, a relatively small adverse move can threaten the position. The precise liquidation price depends on the exchange, contract type, maintenance margin tier, available collateral, funding, and fees. Never treat a simple leverage calculation as a complete liquidation model.
The practical rule is to size the trade from the stop-loss distance first. Decide how much account equity you are willing to lose if invalidated, then calculate the appropriate position size. Margin mode comes after that decision.
For example, if your maximum risk is 0.5% of a $10,000 account, your planned loss is $50. If your technical stop is 1% from entry, your position size should be built so that a 1% move equals roughly $50 before costs. Whether you use isolated or cross margin, that initial risk should remain controlled. Leverage should help you deploy collateral efficiently, not inflate the loss beyond plan.
When Isolated Margin Makes More Sense
Isolated margin is generally the stronger choice when you are trading independent setups, developing a repeatable execution model, or working to eliminate emotional mistakes. It creates a visible boundary between one trade and the rest of the account.
It is particularly useful for traders who tend to average down, move stops, or keep invalidated positions open because liquidation seems distant. Those habits are easier to identify when the trade’s collateral is clearly separated. The position either performs according to plan, is actively managed under a defined rule, or is closed.
For a developing trader, isolated margin reinforces a crucial lesson: account survival is more valuable than extracting the maximum possible profit from one setup.
When Cross Margin Can Be Appropriate
Cross margin can be appropriate for experienced traders managing a defined book of positions rather than a collection of unrelated entries. That may include hedged exposure, basis strategies, or carefully monitored positions where net exposure, correlation, and total drawdown are measured continuously.
It can also suit a trader who needs to avoid unnecessary liquidation from temporary volatility while holding ample collateral and a valid higher-timeframe thesis. But this requires more than confidence. It requires a written risk limit for the entire account, awareness of correlated exposure, and the discipline to reduce risk before a cascade begins.
Cross margin is not inherently aggressive. Unstructured cross margin is aggressive. The difference is whether the trader can explain, before entry, the maximum account drawdown, the relationship between positions, and the exact condition that requires de-risking.
A Disciplined Margin Selection Process
Before placing a leveraged crypto trade, establish the market thesis and invalidation level. Then calculate position size from the amount you are willing to lose, not from the leverage the exchange makes available. Choose isolated margin when the position should stand or fail on its own. Choose cross margin only when you are deliberately managing shared collateral across a coherent portfolio.
Check the exchange’s current maintenance margin rules, liquidation methodology, auto-deleveraging policies, and whether cross collateral is shared across all contracts or only within a specified margin account. Platform mechanics differ, and assumptions made on one exchange may not hold on another.
The margin mode should never be an afterthought selected at the order screen. It is part of the trade architecture, just like identifying external liquidity, waiting for confirmation, and placing a stop beyond meaningful structure.
A disciplined trader does not need every trade to survive. They need each loss to remain small enough that the next high-quality setup can be executed without hesitation.